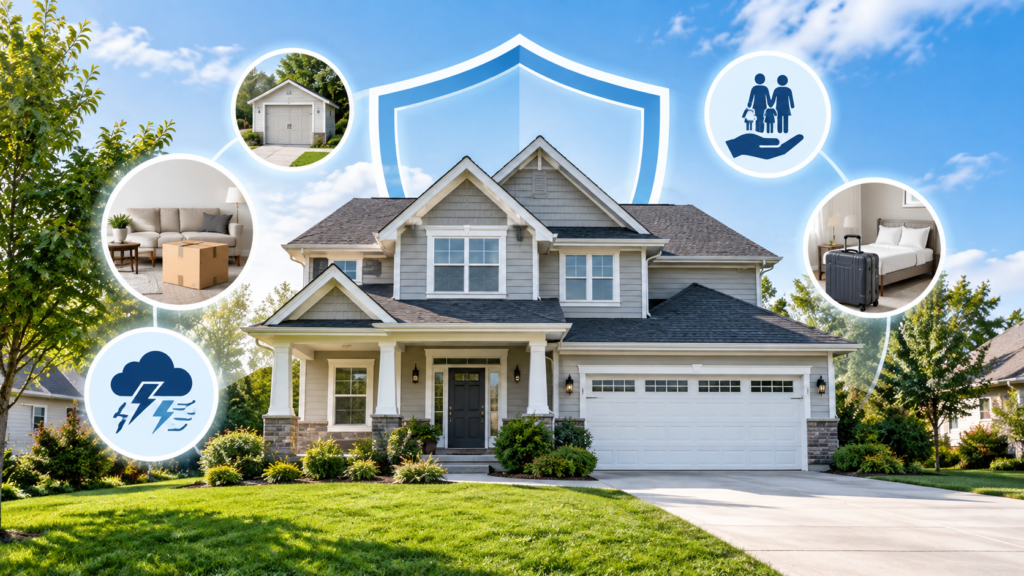
Homeowners insurance can help protect one of your largest financial assets, but understanding what a policy actually covers is not always simple. A typical homeowners policy combines several types of property and liability protection under one policy. The exact protection you receive depends on your policy form, coverage limits, deductibles, endorsements, exclusions, and state-specific requirements.
This guide explains the major parts of homeowners insurance in plain English so you can better understand your policy before comparing coverage options.
What Is Homeowners Insurance?
Homeowners insurance is designed to provide financial protection for your home, your belongings, and certain liability risks. It may help pay to repair or rebuild your home after a covered loss, replace damaged or stolen personal property, cover additional living expenses when your home becomes temporarily uninhabitable, and protect you financially if you are legally responsible for certain injuries or property damage involving other people.
Homeowners insurance is not a home-maintenance plan. Damage caused by normal wear and tear, neglect, deterioration, or other excluded causes generally is not covered simply because you have a homeowners policy.
Mortgage lenders commonly require borrowers to maintain homeowners insurance while a mortgage is outstanding. Even homeowners without a mortgage may choose coverage because rebuilding a home or replacing personal belongings after a major loss can be extremely expensive.
The Main Types of Homeowners Insurance Coverage
Although policy wording varies, homeowners policies commonly include several major coverage categories.
1. Dwelling Coverage
Dwelling coverage protects the physical structure of your home against covered causes of loss.
This can include the main house and structures that are attached to it, such as an attached garage. Built-in systems and fixtures may also fall within dwelling coverage, subject to the policy terms.
For example, if a covered fire seriously damages your home, dwelling coverage may help pay for eligible repairs or reconstruction up to the applicable policy limit.
Your dwelling coverage limit should be based primarily on the estimated cost of rebuilding the home rather than simply its current real-estate market value. Land value is not the same thing as the cost of reconstructing a house.
Construction costs can change over time, so it is useful to review your dwelling limit periodically, especially after major renovations or additions.
2. Other Structures Coverage
This coverage applies to certain structures on your property that are not attached to your house.
Examples may include:
- A detached garage
- Storage shed
- Fence
- Gazebo
- Certain other detached structures
The amount available for other structures is often related to the dwelling coverage limit, although the exact percentage or limit depends on your policy.
If you use a detached structure for business purposes or have an unusual structure on your property, review the policy carefully because special limitations or exclusions may apply.
3. Personal Property Coverage
Personal property coverage can help protect belongings such as:
- Furniture
- Clothing
- Electronics
- Appliances that are not part of the building
- Kitchenware
- Books
- Sporting equipment
- Other household possessions
Coverage may apply when personal property is damaged or stolen because of a covered event, subject to your deductible, policy limit, exclusions, and any special limits.
Some categories of valuable property may have lower special limits than the overall personal-property limit. Examples can include jewelry, watches, collectibles, fine art, firearms, precious metals, or certain business property.
If you own high-value items, ask whether you need additional scheduled property coverage or an endorsement.
Replacement Cost vs. Actual Cash Value
One of the most important concepts in homeowners insurance is how covered property is valued after a loss.
Replacement Cost
Replacement-cost coverage generally aims to pay the cost of repairing or replacing covered property with materials or items of similar kind and quality without subtracting depreciation, subject to the policy’s terms and limits.
For example, if a covered loss destroys an older piece of furniture, replacement-cost coverage may consider the cost of replacing it with a comparable new item rather than only its depreciated value.
Actual Cash Value
Actual cash value, often called ACV, generally takes depreciation into account.
That means the age, condition, and expected useful life of damaged property may reduce the amount payable compared with replacement-cost coverage.
The difference can be significant after a major claim, so check whether your dwelling and personal property are insured on a replacement-cost or actual-cash-value basis.
4. Loss of Use and Additional Living Expenses
If a covered loss makes your home temporarily uninhabitable, loss-of-use coverage may help with certain additional costs of living elsewhere while repairs are being completed.
Depending on the policy, eligible expenses may include reasonable additional costs for:
- Temporary housing or hotel stays
- Increased meal expenses
- Laundry
- Certain transportation expenses
- Other necessary increases in normal living costs
This does not necessarily mean every expense while you are away from home will be covered. Policies contain limits and conditions, and the expense generally must result from a covered loss.
Keep receipts and records if you need to make a loss-of-use claim.
5. Personal Liability Coverage
Homeowners insurance is not limited to damage to your house.
Personal liability coverage may help protect you financially when you are legally responsible for certain bodily injury or property damage suffered by another person.
For example, liability coverage could potentially apply if a visitor is injured on your property and you are found legally responsible, subject to the circumstances and policy terms.
It may help pay covered legal-defense expenses, settlements, or judgments up to the applicable limits.
Liability exclusions are important. Auto-related liability, intentional acts, and some business-related risks generally require different insurance arrangements.
Homeowners with substantial assets may also consider discussing a personal umbrella policy with a licensed insurance professional if they want liability protection above the limits of their underlying policies.
6. Medical Payments to Others
Many homeowners policies include a smaller amount of medical-payments coverage for certain injuries to people who are not members of your household.
This coverage may help pay eligible medical expenses following a covered incident without requiring the same determination of legal liability that is generally involved in a liability claim.
The limits tend to be lower than personal-liability limits, so review your declarations page to see exactly how much coverage your policy provides.
What Events Does Homeowners Insurance Cover?
Insurance policies refer to causes of loss as “perils.”
Depending on the policy form, coverage may be written for specifically named perils or may cover a broader range of risks except those that the policy expressly excludes.
Common covered causes of loss can include events such as:
- Fire
- Lightning
- Windstorm
- Hail
- Smoke
- Theft
- Vandalism
- Certain types of sudden accidental damage
However, coverage depends on the exact policy. Never assume that an event is covered merely because another homeowners policy covers it.
Read the policy and declarations page or ask your insurer or licensed agent when you are uncertain.
What Homeowners Insurance Commonly Does Not Cover
A homeowners policy does not cover every possible type of damage.
Flooding
Standard homeowners insurance generally does not cover flooding caused by rising surface water or similar flood events.
Homeowners who need this protection may purchase separate flood insurance through the National Flood Insurance Program or, where available, from private insurers.
Do not confuse flood damage with every form of water damage. Some sudden and accidental water losses may be treated differently under a homeowners policy. The cause of the water damage is important.
Earthquakes
Standard homeowners policies also generally exclude earthquake damage.
Earthquake coverage may be available through a separate policy or an endorsement, depending on the insurer and location.
Normal Wear and Tear
Homeowners insurance is intended primarily for covered accidental losses, not routine maintenance.
Examples of problems that may not be covered when caused by deterioration or lack of maintenance include:
- Aging roofs
- Rot
- Corrosion
- Long-term leaks
- General deterioration
- Pest-related damage in many circumstances
Maintaining your home remains your responsibility even when it is insured.
Understanding Your Deductible
A deductible is the amount you are responsible for paying toward a covered property loss before insurance pays the remaining eligible amount, subject to the policy terms.
For example, if you have a $1,000 deductible and an eligible covered loss is valued at $6,000, the deductible generally reduces the insurer’s payment.
Some policies may use different deductibles for certain risks, such as windstorms, hurricanes, or other catastrophe-related losses. These deductibles can sometimes be expressed as a percentage rather than a flat dollar amount.
A higher deductible can reduce premiums in some situations, but it also means you may need to pay more out of pocket when a covered loss occurs.
Choose a deductible you could reasonably afford following an unexpected event.
Policy Limits Matter
Every homeowners policy has coverage limits.
The limit represents the maximum amount the insurer may pay for a particular coverage, subject to the terms of the policy and the circumstances of the claim.
Do not assume your policy automatically increases every time construction costs or the value of your possessions rise.
Review limits after events such as:
- A major home renovation
- Building an addition
- Installing an expensive kitchen
- Purchasing valuable belongings
- Adding a detached structure
- Major changes in local rebuilding costs
Discuss significant changes with your insurer or licensed insurance professional.
Consider Creating a Home Inventory
A home inventory is a record of your possessions.
It can include photographs, videos, receipts, serial numbers, purchase dates, and approximate values.
Keeping an inventory may make it easier to identify what was lost after a theft, fire, or other major covered event.
Store a copy somewhere that would remain accessible even if your home were severely damaged—for example, in secure cloud storage or another safe location.
Update your inventory when you purchase expensive items.
Optional Endorsements and Additional Coverage
A standard homeowners policy may not meet every household’s needs.
Depending on the insurer and state, optional coverage may be available for risks such as:
- Water or sewer backup
- Valuable jewelry and collectibles
- Identity-related expenses
- Equipment breakdown
- Increased rebuilding costs
- Certain home-business exposures
- Earthquake damage
Availability, terminology, limits, and exclusions vary considerably.
An endorsement modifies the underlying insurance contract, so read it carefully rather than assuming it provides unlimited protection.
How Much Homeowners Insurance Do You Need?
There is no single coverage amount that is right for every homeowner.
When reviewing coverage, consider several different risks separately.
For the dwelling, focus on the estimated cost to rebuild the home after a total covered loss.
For personal property, consider the value of the belongings you would need to replace.
For liability coverage, consider your financial situation and the amount of protection you would want if you were legally responsible for a serious covered injury or property-damage claim.
The cheapest policy is not necessarily the best fit. Compare coverage limits, deductibles, exclusions, endorsements, claim provisions, and insurer service—not only the premium.
If you are shopping for coverage, take time to compare home insurance options from different providers. Look beyond the premium and consider the coverage limits, deductibles, exclusions, optional endorsements, and other policy features that may affect your protection.
Questions to Ask When Comparing Homeowners Insurance
Before choosing a policy, consider asking:
- Is the dwelling insured for replacement cost or actual cash value?
- How is personal property valued after a claim?
- What is the deductible?
- Are there separate wind, hurricane, or other deductibles?
- Which causes of loss are covered?
- Which exclusions are especially important?
- What are the limits for jewelry and other valuable property?
- Is water or sewer backup covered?
- Is flood insurance separate?
- Is earthquake coverage available?
- How much liability protection does the policy include?
- Are additional living expenses subject to a dollar or time limit?
- What optional endorsements are available?
Comparing these details can provide a clearer picture than comparing premium prices alone.
Review Your Policy Regularly
Your insurance needs can change.
Review your homeowners coverage periodically and after major life or property changes.
Consider contacting your insurer or licensed agent after:
- Remodeling or expanding your home
- Purchasing expensive property
- Installing a pool or other significant feature
- Changing how the home is occupied
- Beginning a home-based business
- Renting out all or part of the property
- Making other substantial changes to the home
A policy that was appropriate several years ago may not provide the same level of protection today.
Frequently Asked Questions
Does homeowners insurance cover everything in my house?
No. Coverage is subject to policy limits, deductibles, exclusions, and special limits for certain categories of property. Some high-value belongings may require additional coverage.
Does homeowners insurance cover flooding?
Standard homeowners policies generally do not cover flood damage from rising surface water. Separate flood insurance may be available.
Does homeowners insurance cover earthquakes?
Earthquake damage is generally excluded from standard homeowners policies. Separate earthquake insurance or an endorsement may be available.
What is the difference between replacement cost and actual cash value?
Replacement-cost coverage generally does not subtract depreciation when determining the cost of replacing covered property with comparable property, while actual cash value generally accounts for depreciation. Policy conditions and limits still apply.
Does homeowners insurance cover temporary housing?
If your home becomes uninhabitable because of a covered loss, loss-of-use or additional-living-expense coverage may help pay certain increased living costs, subject to policy limits and conditions.
Should I choose homeowners insurance based only on price?
Price is important, but it should not be the only consideration. Compare deductibles, coverage limits, exclusions, valuation methods, optional endorsements, and insurer service as well.
The Bottom Line
Homeowners insurance can combine protection for your house, detached structures, belongings, temporary living expenses, personal liability, and certain medical expenses. But every policy has limits and exclusions.
Before buying or renewing coverage, understand what your policy covers, what it excludes, how deductibles work, and whether claims are settled using replacement cost or actual cash value.
Pay particular attention to major risks such as floods and earthquakes, which generally require separate coverage. Review your policy as your home and financial circumstances change, and speak with a licensed insurance professional when you need advice about your individual situation.